
Upcoming posts (in no particular order): PayPal/Stripe, IAC, Gartner, Red Violet, Verisk, Visa/Mastercard
Payment processing stocks on the whole have had a rough 12 months:
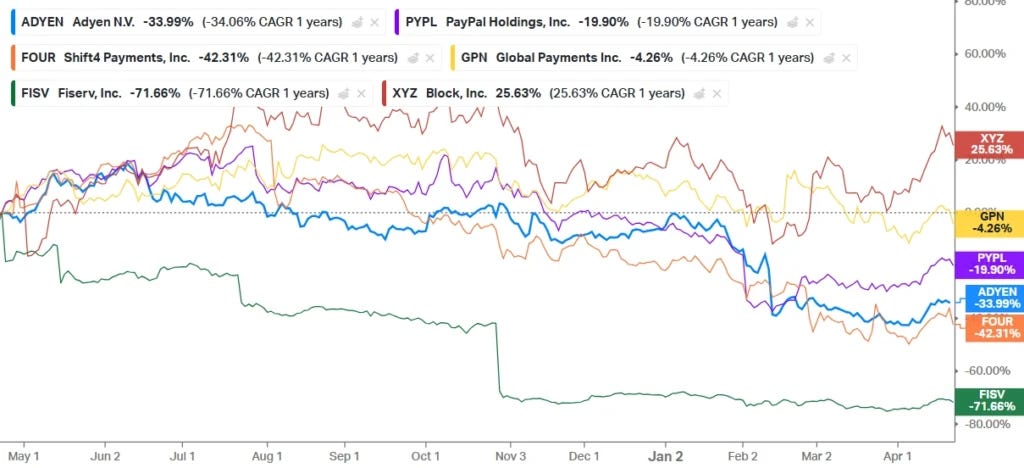
For some of these names, one can propose idiosyncratic reasons that might explain the sell-off – Shift4 is an opaque and levered serial acquirer; Global Payments and Fiserv are sclerotic, share-donating incumbents; PayPal took an ambitious strategy and executed it disastrously. Adyen, by contrast, operates a unified, organically developed platform, unencumbered by debt and guided by operators with skin in the game. But its stock, too, has collapsed. Having swooned 65% from the highs, it is not much higher than it was 6 years ago, even as payment volumes have sextupled and EBITDA has quintupled. This can sometimes happen to a stock that starts off at ~125x earnings!
Adyen’s commercial success has been supported by 2 unique pillars that should be familiar to most of us by now.
First, unlike legacy merchant acquirers, who spent decades assembling a patchwork of disparate providers through M&A, Adyen created, entirely in-house, a single unified that extends across all its markets. Whereas First Data and Global Payments, which operate more like an archipelago of payment platforms, must build the same product or feature multiple times to accommodate different code bases, Adyen need only do so once.
Second, whereas most peers, including modern PSPs like Stripe, still rely on aggregators and BIN rentals to serve different markets, Adyen holds banking licenses in every country in which it operates, giving it greater visibility into transaction details, which in turn translates to superior authorization rates. As I explained in some thoughts on Adyen:
Combining the gateway with merchant acquiring and processing means Adyen can underwrite merchants according to their own compliance standards and save on fees they would otherwise pay a third party acquirer. But more importantly, it gives them greater visibility into and control over the payments flow.
As an acquiring bank with direct access to card rails, Adyen can iteratively tweak messaging details in an authorization request to improve the chances that the issuer bank will accept it. If a payment fails due to a connection issue at the level of the acquiring bank or processor, they can more easily see and rapidly fix it than most other payment service providers, who obviously can’t inspect the systems of the acquiring banks they rent BINS from. Adyen, more so than any other PSP, is very opinionated about owning the full stack. They would rather not process payments in a country at all than gateway to third party acquirers, whose variable performance dilutes their exacting service standards.
These do not, on the surface, seem like much of a moat. Stripe, First Data, or any other processor could have made the same architectural and strategic choices early in their lives. I suspect one underappreciated reason they didn't is that the payments industry is saturated with FOMO. There is always a plausible-sounding urgent narrative for why BNPL or crypto or digital wallets or some other new thing needs to be squeezed into your roadmap now. Whether due to a cautious European temperament or the personality quirks of its founders, Adyen stands apart in its restraint. As competitors acquired targets in a frenzied attempt to keep pace with the latest themes, Adyen dedicated itself to strengthening its two foundational pillars, recognizing that a unified tech stack and vertical integration would remain relevant regardless of what new payment fashions emerged.
That discipline has produced a genuinely differentiated product. But Adyen prices for it accordingly, which has invited a familiar critique. Some have argued that in a competitive US market where payments is often treated as a commodity, Adyen’s relatively high processing fees are unsustainable. That concern came to a head in August 2023, when the company swiftly shed ~60% of its market cap after management cited increasing competitive pressure in North America. Net revenue growth there had decelerated sharply from 45% in 2h22 to 23% in 1h23. PayPal was partly to blame, having effectively given away Braintree processing at cost in an effort to drive volumes toward its higher-margin branded checkout button. It didn’t help that EBITDA margins were simultaneously compressed by an aggressive hiring spree that had not yet been absorbed.